



 Limited to 100 registrants
Inventory is important for meeting customer demand and keeping operations running smoothly. However, holding too much stock can increase costs and reduce efficiency. Businesses need the right balance between enough stock and controlled costs.
Many companies see inventory as an asset, but excess stock can tie up cash and create waste. Slow-moving items may also lead to discounts or write-offs.
Inventory cost includes more than the purchase price. It also covers storage, handling, insurance, and damage risks. Understanding these costs helps businesses improve profit and cash flow.
Key Takeaways
Inventory cost covers far more than the purchase price, as it also includes storage, handling, insurance, and the risk of damage or obsolescence.
These costs directly shape profit margins, cash flow, and inventory turnover, so keeping them under control strengthens overall financial health.
Inventory expenses fall into three main categories: purchase and production costs, carrying and holding costs, and ordering and replenishment costs.
Excess stock, slow-moving items, inefficient storage, and demand uncertainty rank among the most common drivers behind rising inventory costs.
What Is Inventory Cost?
Inventory cost refers to all expenses involved in purchasing, producing, storing, and managing stock before it is sold or used. It includes more than just the product price, covering every cost linked to keeping inventory available.
For manufacturers, inventory costs may include raw materials, labour, and finished goods. For wholesalers and retailers, it often includes purchased goods, warehousing, and replenishment expenses.
Understanding inventory cost helps businesses price products accurately, protect profit margins, and avoid tying up too much cash in excess stock.
Using a inventory management platform is optimal for business to manage their inventory cost by streamlining processes and utilizing resources optimally.
Why Inventory Cost Matters More Than You Think
Inventory costs can affect more than stock levels alone. They influence profitability, cash flow, and how efficiently inventory moves through the business.
1. Impact on profit margins
Unnecessary inventory expenses such as storage fees, spoilage, and rising supplier prices can reduce gross profit. If costs increase faster than pricing adjustments, margins become harder to maintain.
2. Effect on cash flow
Money tied up in inventory cannot be used for payroll, marketing, or business growth. Excess stock can create cash flow pressure even when sales remain steady.
3. Link to inventory turnover
Low inventory turnover often means products are moving too slowly. This increases holding costs and raises the risk of obsolete stock.
"Understanding inventory cost is key to improving profitability, cash flow, and operational efficiency. Businesses that actively manage these costs gain better control over their supply chain and long-term growth."
Breaking Down Inventory Costs
Understanding inventory cost starts with knowing what expenses contribute to it, making it one of the core principles of stock management. While many businesses focus on purchase price alone, inventory costs also include several other components that directly affect profitability.
1. Purchase and production costs
These costs include supplier pricing, freight charges, raw materials, direct labour, and manufacturing overheads. They form the base cost of acquiring or producing stock.
2. Carrying and holding costs
Holding costs include warehouse rent, utilities, insurance, financing costs, and losses from damage or theft. These expenses grow when inventory sits too long.
3. Ordering and replenishment costs
These costs cover procurement tasks such as placing orders, receiving goods, inspections, and system processing. Frequent ordering can increase administration costs.
What Makes Inventory Costs Increase
Inventory expenses often rise because of avoidable operational issues. Identifying the main causes helps businesses reduce waste and improve control.
1. Excess stock and slow-moving items
Overstocking ties up cash and uses valuable warehouse space. Slow-moving items often need markdowns or write-offs before they are sold.
2. Inefficient storage and handling
Poor warehouse layouts and manual processes can increase labour time and handling costs. They also raise the chance of damaged inventory.
3. Demand uncertainty
Inaccurate forecasting makes it harder to maintain the right stock levels. This can result in shortages or costly overstock situations.
The Hidden Costs of Holding Inventory
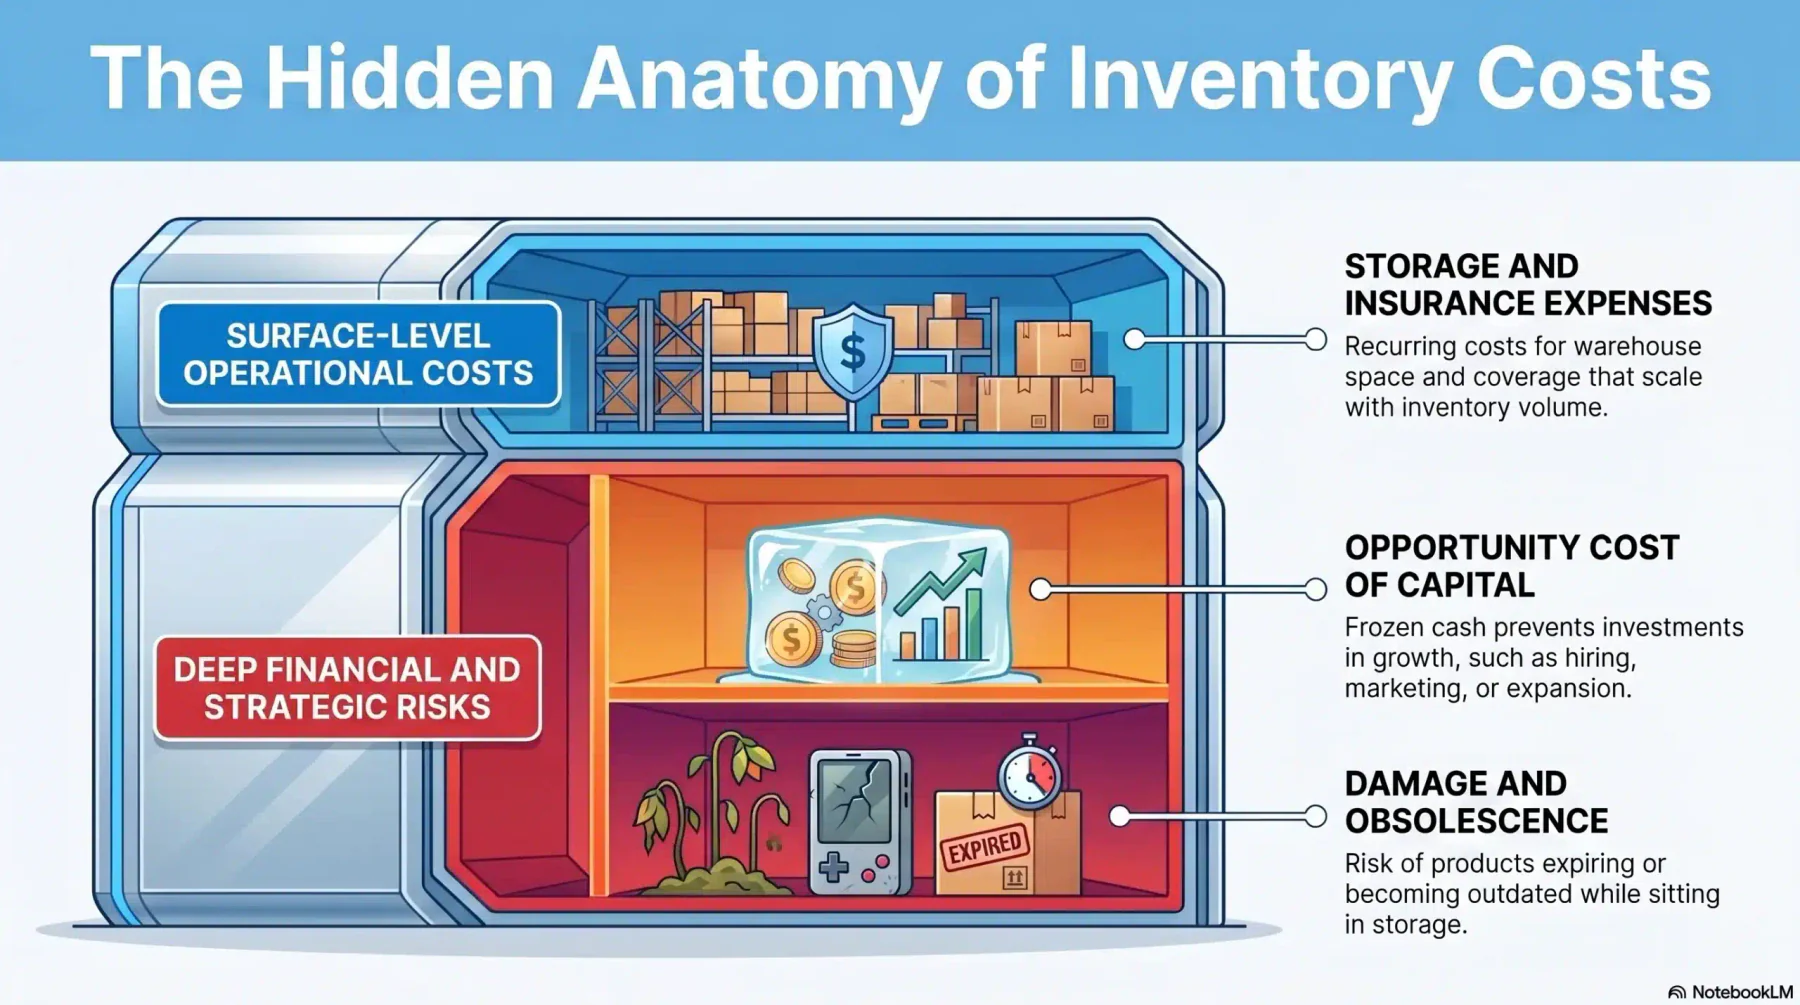
Some inventory costs are easy to see, while others are often overlooked. These hidden expenses can quietly reduce profits over time.
1. Opportunity cost of capital
Cash invested in inventory cannot be used for other priorities such as hiring staff, marketing, or expansion. This can limit growth opportunities.
2. Risk of damage and obsolescence
Products may expire, become outdated, or lose value while in storage. This risk is especially high for seasonal or technology-based items.
3. Storage and insurance expenses
Higher stock levels usually require more warehouse space and insurance coverage. These recurring costs can build up over time.
How Inventory Cost Is Measured
Measuring inventory cost helps businesses track performance and make better decisions. Clear cost data also supports stronger planning and budgeting.
1. Understanding cost components
Businesses often measure inventory cost by separating product cost, ordering cost, holding cost, and overhead expenses. This creates clearer visibility into spending.
2. Inventory carrying cost formula
A common formula is Inventory Carrying Cost = Average Inventory Value × Carrying Cost Rate. It helps estimate the annual cost of holding stock.
3. Interpreting cost as a percentage
Many businesses express carrying cost as a percentage of total inventory value. Higher percentages often indicate overstocking or inefficient inventory control.
4. Inventory valuation and cost reporting
The inventory valuation approaches a business chooses, whether FIFO, LIFO, or weighted average cost, directly determines how inventory costs are recorded and reported.
This affects both the cost of goods sold and the ending inventory value on the balance sheet.
How AASB 102 Affects Inventory Valuation for Australian Businesses
Inventory cost reporting in Australia does not follow personal preference; it follows AASB 102 Inventories, the accounting standard that governs how businesses measure and disclose stock. Understanding these rules helps Australian businesses keep their inventory cost figures compliant, comparable, and ready for audit.
The areas below explain what the standard requires and how each rule shapes the inventory cost a business reports.
What AASB 102 Requires for Inventory Measurement
AASB 102 requires businesses to measure inventory at the lower of cost and net realisable value. Cost covers the purchase price, conversion costs, and other costs of bringing stock to its present location and condition. This principle sets the foundation before any specific costing method applies.
Approved Cost Formulas: FIFO and Weighted Average
The standard permits two cost formulas for interchangeable inventory: first-in first-out (FIFO) and weighted average. A business chooses the formula that best reflects how its stock actually flows, then applies it consistently to similar items. Specific identification applies instead to items that are not ordinarily interchangeable.
Why LIFO Is Not Permitted in Australia
AASB 102 does not allow last-in first-out (LIFO), which sets Australian practice apart from US GAAP. LIFO can leave very old costs on the balance sheet and distort inventory cost when prices rise. Therefore, Australian businesses weighing tax or valuation decisions cannot rely on it, and international reporting follows the same position under IAS 2.
Net Realisable Value (NRV) Write-Downs
When the selling price of stock falls below its recorded cost, AASB 102 requires a write-down to net realisable value. NRV is the estimated selling price less the costs to complete and sell the goods. This write-down increases the reported inventory cost expense and lowers the carrying amount on the balance sheet.
Disclosure Requirements for Inventory Cost
AASB 102 requires businesses to disclose the cost formula used, the total carrying amount of inventory, and the value of any write-downs recognised in the period. Clear disclosure lets auditors, lenders, and investors compare inventory cost fairly across reporting periods. The Australian Taxation Office also sets its own trading stock valuation rules that sit alongside these accounting requirements.
What This Means for Australian SMEs Managing Inventory Cost
For growing Australian businesses, AASB 102 makes inventory cost a compliance matter as well as an operational one. Consistent costing methods, regular NRV reviews, and reliable records keep both the books and the tax position defensible. Inventory management software helps smaller businesses apply these rules without reconciling every figure by hand.
Using Inventory Cost Data for Decisions
Inventory cost data should be used as a decision-making tool, not just for reporting. It helps businesses plan stock levels, reorders, and product strategies.
1. Setting optimal stock levels
Businesses can use cost data to balance product availability with lower carrying costs. This helps avoid both shortages and excess stock.
2. Planning reorders and safety stock
Proper reorder points and safety stock levels reduce the risk of stockouts. They also help prevent emergency purchases at higher prices.
3. Identifying high-cost products
Some products are expensive to store or move too slowly. Identifying them helps businesses improve pricing, promotions, or product range decisions.
Strategies to Reduce Inventory Cost
Reducing inventory cost is about improving efficiency rather than simply cutting stock. The right strategies can lower expenses while maintaining service levels.
1. Improving demand forecasting
Proper inventory forecasting techniques uses sales history and market trends to predict future demand. This helps reduce both shortages and excess inventory.
2. Optimizing stock levels
Methods such as EOQ, ABC analysis, and SKU reviews help maintain efficient stock levels. These approaches reduce unnecessary carrying costs.
3. Using inventory management systems
Modern systems provide real-time visibility into stock levels and movements. They also improve planning accuracy and reduce manual errors.
Before choosing an inventory software, you should create your own inventory platform shortlist that aligns with your operations.
An integrated inventory platform connects purchasing, warehouse, sales, and accounting data. This helps teams respond faster to stock changes and maintain consistent records across locations.
AI-powered tools can also flag unusual movements, anticipate replenishment needs, and improve forecasting. Try a free demo and consultation to see how the system supports your inventory workflow.

Conclusion
Inventory cost has a direct impact on profit, cash flow, and overall business efficiency. It includes more than the purchase price of stock, covering storage, handling, financing, and risk-related expenses.
When these costs are not managed properly, they can reduce margins and tie up valuable working capital. Poor inventory control can also lead to waste, slow-moving stock, and unnecessary spending.
By understanding inventory cost and improving stock management, businesses can make smarter decisions and reduce waste. With the right strategy, inventory becomes a stronger asset that supports growth.
Get consultation without charge to better understand your inventory costs and find practical ways to improve efficiency and profitability in your business.
Frequently Asked Question
Inventory cost includes the purchase price of goods plus extra costs like storage, handling, transport, insurance, and risk of damage or obsolescence.
Inventory cost is important because it affects profit and cash flow. High costs or slow-moving stock can reduce available cash and lower profitability.
Businesses can reduce inventory cost by improving demand forecasting, avoiding excess stock, and using inventory management systems to track and control stock more efficiently.