
Have you ever checked your business bank balance and thought everything looked fine, only to face unpaid bills or delayed revenue? Stronger financial management practices were associated with more reliable financial reporting, showing why cash visibility alone can mislead growing businesses.
Cash basis accounting records revenue and expenses when money changes hands. This approach gives small businesses a straightforward view of cash activity. Department of Trade and Industry (DTI) encourages business owners to build clearer financial practices as operations grow and unpaid invoices, upcoming bills, and other obligations become harder to track.
Read on to learn the advantages and limitations of cash basis accounting, compare it with accrual accounting, and decide which method fits your business. We also cover practical controls and software options that can improve financial visibility as your company grows.
Key Takeaways
Cash basis accounting records income when cash is received and expenses when payments are made, making it suitable for businesses that prioritise simple bookkeeping and cash-flow visibility.
Businesses using cash basis accounting recognise transactions when money changes hands, while tracking unpaid invoices, outstanding bills, inventory, and future obligations separately.
Cash basis accounting simplifies recordkeeping and improves cash-flow tracking but may provide an incomplete view of financial performance and future obligations.
HashMicro’s Accounting Software helps businesses manage cash basis accounting through automated tracking, real-time bank integration, and BIR-compliant reporting.
What is Cash Basis Accounting?
Cash basis accounting, also called cash-based accounting, records income only when a business receives cash. It records expenses only when the business makes payments. Many Philippine small businesses use this straightforward method because it tracks available cash without recording outstanding accounts receivable or accounts payable.
This approach suits freelancers, consultants, and small retailers that mainly handle cash transactions. It shows how much money the business can use at a given time. However, it excludes credit income until customers pay, which can hide expected revenue.
Cash basis accounting offers simplicity, but it may not show a growing company’s complete financial position. It can also limit tax reporting and financial planning. Businesses should understand the accrual accounting method before switching to meet regulatory, lender, or investor requirements.
How does Cash Basis Accounting Work for Business?
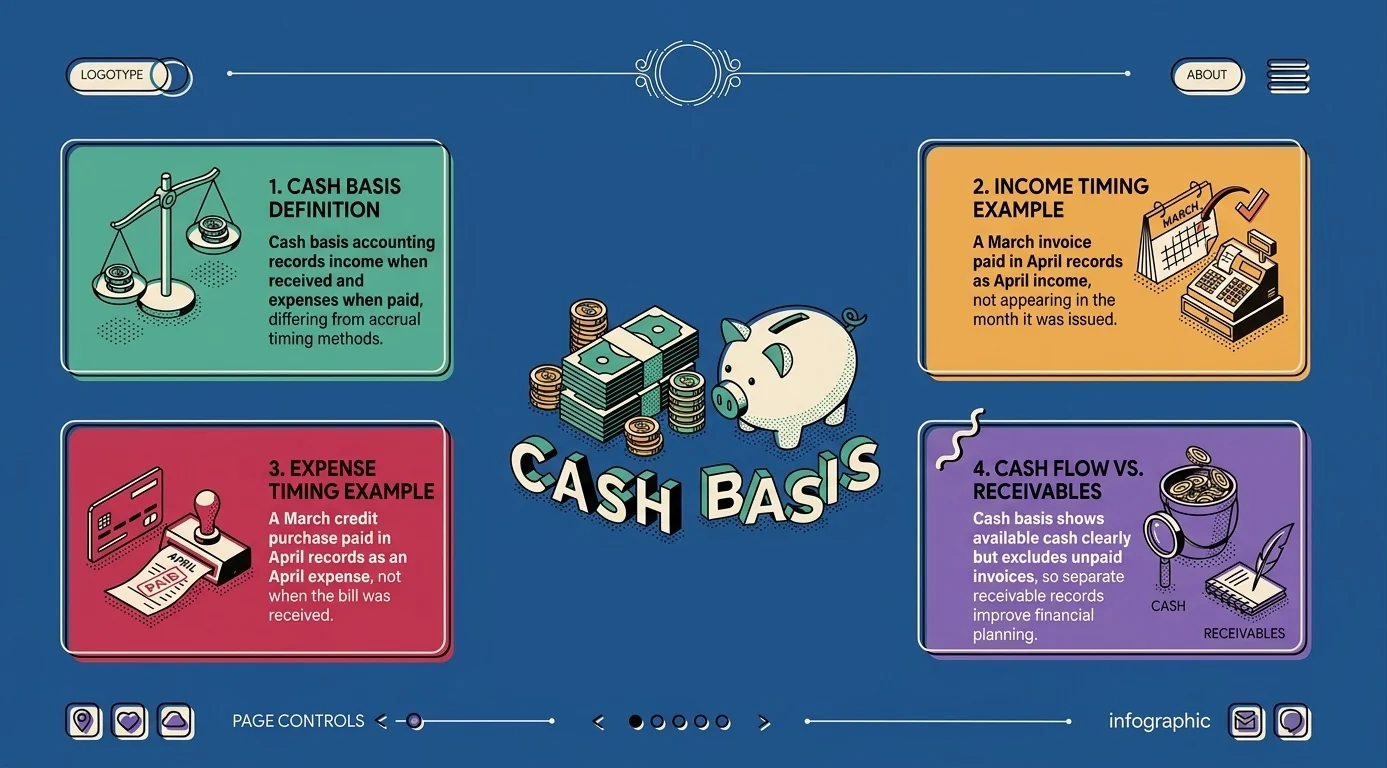
Cash basis accounting records income when a business receives payment and expenses when it pays. This timing differs from accrual accounting, which records transactions when they occur. The method helps small businesses monitor cash flow, but it excludes unpaid invoices and bills from current records.
Cash basis accounting follows a simple rule: recorded income equals cash received, while recorded expenses equal cash paid. The examples below show how businesses apply this rule to customer payments and credit purchases.
Customer payment example:
- Step 1: A company issues an invoice in March.
- Step 2: The customer receives the invoice but pays in April.
- Step 3: The company records the income when it receives the payment.
- Step 4: The March invoice does not appear as income in March.
Credit purchase example:
- Step 1: A company buys supplies on credit in March.
- Step 2: The supplier sends the bill in March.
- Step 3: The company pays the bill in April.
- Step 4: The company records the expense in April, not March.
This process gives owners a clear view of available cash during daily operations. However, it does not show expected revenue or unpaid obligations. Businesses can use cash basis accounting for simple transactions, but separate accounts receivable and payable records can improve financial planning.
Example of Cash Basis Accounting
Cash basis accounting records income when a business receives payment and expenses when it makes payment. It does not record invoices or bills when issued. This approach helps small businesses track actual cash flow and understand how much money remains available for daily operations.
Download the free cash basis accounting sheet template to organize your daily transactions and improve financial tracking:
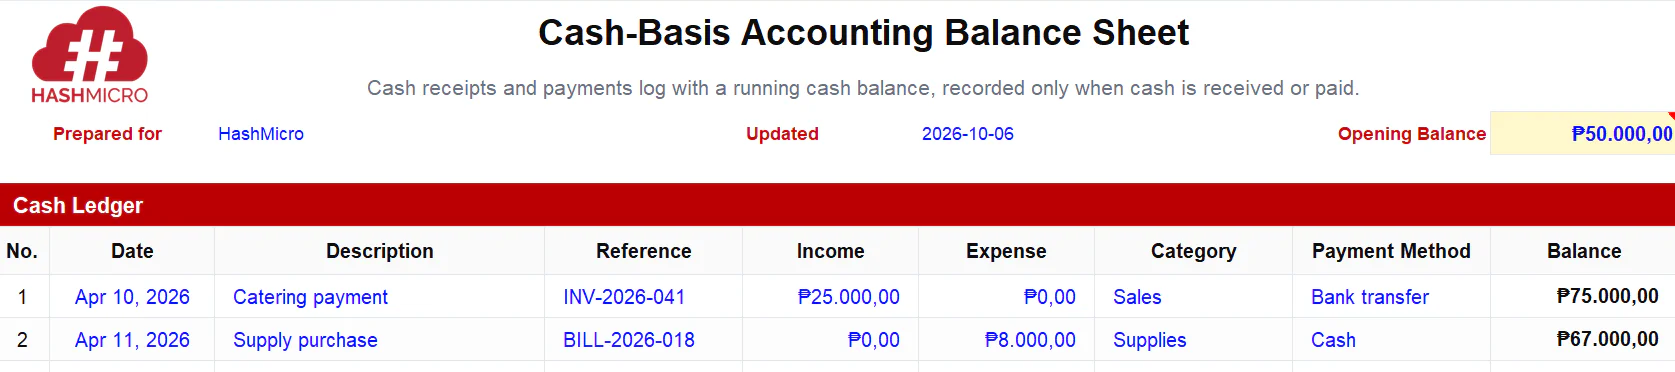
Use a cash basis accounting sheet to record every cash transaction in one place. The template with a cash basis example can help you monitor income, expenses, categories, and running balances without managing complex accounts receivable or payable records.
Components of a Cash Basis Accounting Sheet
| Date | Description | Reference | Income | Expense | Category | Payment Method | Balance |
|---|---|---|---|---|---|---|---|
| Apr 10, 2026 | Catering payment | INV-2026-041 | ₱25,000 | ₱0 | Sales | Bank transfer | ₱75,000 |
| Apr 11, 2026 | Supply purchase | BILL-2026-018 | ₱0 | ₱8,000 | Supplies | Cash | ₱67,000 |
- Date
Records when the business receives or pays cash.
Example: April 10, 2026
- Description
Explains the transaction.
Example: Customer payment for catering order
- Reference Number
Connects the entry to an invoice, receipt, or payment record.
Example: INV-2026-041
- Income
Shows cash received by the business.
Example: ₱25,000
- Expense
Shows cash paid for business costs.
Example: ₱8,000
- Category
Groups transactions by their business purpose.
Example: Sales, Rent, Supplies, or Transportation
- Payment Method
Identifies how the business received or paid cash.
Example: Cash, Bank transfer, or GCash
- Running Balance
Shows the remaining cash after each transaction.
Example: ₱50,000 + ₱25,000 - ₱8,000 = ₱67,000
What are the Pros and Cons of Cash Basis Accounting?
For businesses in the Philippines, choosing an accounting method affects how owners measure performance, manage taxes, and plan growth. Cash basis accounting offers simple records and clear cash visibility. However, it can hide unpaid invoices and obligations. The following pros and cons explain when this method fits and where it creates risks.
Pros of Cash Basis Accounting
- Simple to use and understand: Cash basis accounting records transactions when money changes hands. This straightforward process suits freelancers, sole proprietors, and small businesses with uncomplicated finances.
- Real-time cash flow visibility: The method shows money received and spent during a specific period. Owners can quickly assess available cash for payroll, supplies, utilities, and other daily needs.
- Potentially easier tax planning: Businesses recognize income when they receive payment. This approach may help owners manage cash availability when customers pay at different times. However, Philippine tax obligations can follow specific BIR rules.
- Lower administrative burden: Cash basis requires fewer entries than accrual accounting. Small businesses can reduce paperwork and simplify bookkeeping without hiring a full-time accounting team.
Cons of Cash Basis Accounting
- Incomplete financial picture: Cash basis accounting excludes unpaid invoices and outstanding bills. This can make the business look weaker or stronger than it really is.
- Misleading cash flow signals: Expenses may appear before related income. Owners may misread performance, overdraw funds, or invest money needed for upcoming obligations.
- Financing challenges: Lenders and investors may question records that exclude receivables, payables, and true liabilities.
- Limited planning insight: The method weakens forecasting and long-term decisions. Review a down payment strategy before major purchases or financing plans.
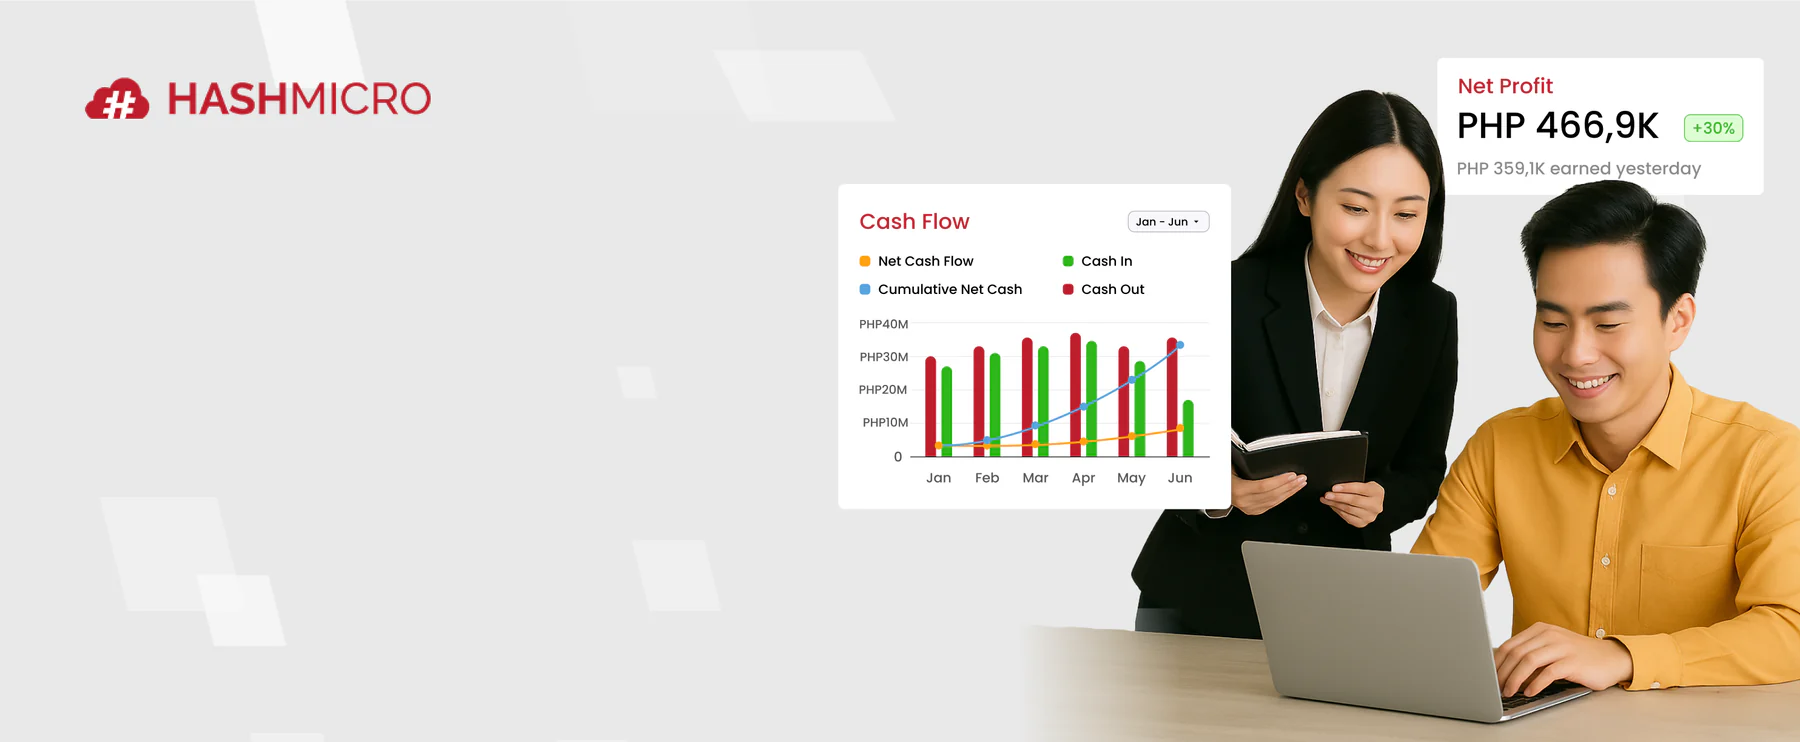
Cash basis accounting simplifies bookkeeping, improves cash flow visibility, and reduces administrative work for small businesses. As transactions grow, HashMicro accounting software can help you maintain this visibility while organizing records, automating routine tasks, and supporting more efficient financial management.
When is Cash Basis Accounting a Good Fit?
Cash basis accounting suits businesses that receive and pay money quickly. In the Philippines, sole proprietors, freelancers, micro-businesses, small partnerships, retailers, and service providers often choose it. The method keeps records simple, reduces administrative work, and helps owners track available cash without managing complex receivables or payables.
- Small businesses with simple transactions: Cash basis accounting helps small enterprises and sole proprietors record routine sales and expenses without complex inventory or financial reporting processes.
- Retailers and service providers paid upon sale: Sari-sari stores, local retailers, small clinics, and service professionals can match recorded income with received customer payments.
- Freelancers and early-stage startups: Cash basis reduces bookkeeping tasks and helps independent professionals monitor cash inflows and outflows without a full-time finance team.
- Businesses evaluating their accounting method: Entrepreneurs managing multiple entities can select cash basis or accrual accounting according to each business's transactions, needs, and reporting requirements.
Cash basis appeals to owners because it records transactions only when they receive or pay cash. The method streamlines bookkeeping and reduces accounts receivable and payable tracking, which suits businesses with steady cash flow and limited financial complexity.
However, cash basis may not suit every entity or growth stage. Entrepreneurs managing several businesses should assess each entity's transaction volume, reporting needs, and regulatory obligations. They can choose between cash basis and accrual accounting when permitted, then review the method as operations become more complex.
When Cash Basis Might Not Suit Your Business
While cash basis accounting can be helpful for many small businesses in the Philippines, it isn’t always the best fit, especially for companies with more complex financial needs. Below are several scenarios where cash based accounting may fall short and switching to accrual may be a smarter move.
- You manage large inventories: Businesses that buy and sell significant stock may need detailed inventory accounting. Cash basis accounting does not show inventory movements, unpaid supplier bills, or the full cost of goods sold when transactions occur.
- You offer credit terms to customers: Cash basis accounting delays revenue recognition until customers pay. This can make sales performance appear lower than it is and complicate financial planning.
- You have complex financial obligations: Recurring payables, long-term contracts, and multiple revenue streams require broader financial tracking. Cash basis accounting may overlook upcoming liabilities and expected income.
- You seek external funding or investors: Lenders and investors often prefer accrual-based reports because they show receivables, payables, liabilities, and profitability more comprehensively.
- You need deeper financial insights: Growing businesses may need to analyze profitability beyond their bank balance. Accrual accounting provides a clearer view of performance across accounting periods.
How does Cash-Based Accounting Affect Tax Reporting?
Cash basis accounting records income when customers pay and expenses when businesses pay bills. This timing can simplify tax reporting for Philippine small businesses. However, owners must understand its effect on taxable income, deductions, and year-end planning before applying tax accounting rules to cash-to-cash operations.
1. Income Recognition Aligns With Cash Received
Under cash basis accounting, businesses report income when they receive payment, not when they issue an invoice. This timing can delay taxable income until the customer settles the balance.
Cash basis example: A company completes a service in December but receives payment in January. The business records and reports the income in January, subject to applicable tax rules.
2. Expense Deductions Apply When Businesses Pay
Businesses generally record expenses when they make payment, not when they receive a supplier invoice. This approach keeps expense records aligned with actual cash movements.
Cash basis example: A company receives a marketing invoice in December but pays it in January. The business records the expense in January, when it settles the bill.
3. Tax Planning Requires Careful Timing
Cash basis accounting gives business owners some control over when they recognize income and expenses. They may plan invoice collections and payments around reporting periods, provided their actions follow applicable tax regulations.
However, owners should not delay invoices or payments only to reduce taxable income. They should confirm the reporting requirements with a qualified tax professional before making year-end timing decisions.
4. Tax Filing Becomes Simpler
Cash basis accounting can simplify tax filing because businesses do not need to include unpaid invoices or outstanding bills in their current cash records. This reduces the amount of receivable and payable tracking required.
The method can also reduce bookkeeping work for freelancers and small businesses with simple transactions. However, owners should maintain accurate receipts, payment records, and supporting documents to support their tax returns.
How Can Businesses Transition from Cash-Based to Accrual Accounting?
As your Philippine business grows, moving from cash basis accounting to accrual accounting can improve financial visibility. The transition helps you track receivables, payables, and deferred income more accurately. Follow these steps to prepare your records, update processes, and manage reporting changes with greater confidence.
1. Review Existing Records
Review your cash basis accounting records for accuracy before changing methods. Check sales, expenses, bank balances, unpaid invoices, and outstanding bills. Correct missing or duplicated entries first so your opening accrual records reflect reliable information and reduce conversion problems.
2. Prepare an Opening Balance Sheet
Prepare an opening balance sheet that lists assets, liabilities, and equity at the conversion date. Include accounts receivable, accounts payable, prepaid expenses, and unearned revenue. These balances establish the foundation for recognizing transactions under accrual accounting.
3. Upgrade Your Accounting System
Digital tools can reduce manual work and improve reporting consistency. Update your accounting system to support accrual entries, adjusting journals, receivables, payables, and deferred income. Review existing workflows, user permissions, and chart-of-accounts settings before recording new transactions.
4. Consult an Accounting Professional
Consult an accountant before finalizing the conversion, especially if your business has multiple income sources, inventory, contracts, or branches. A professional can review opening balances, recommend adjusting entries, and explain how the change may affect financial statements and tax obligations.
5. Revisit Your Tax Strategy
Revisit your tax strategy because accrual accounting may change when income and expenses appear in reports. Confirm applicable Philippine tax requirements with a qualified tax advisor. Compare accounting records with tax records to prevent inaccurate filings, unexpected liabilities, or duplicated deductions.
6. Train Your Finance Team
Train finance staff to record revenue when earned and expenses when incurred, even when payment happens later. Explain how to manage receivables, payables, prepaid costs, and deferred income. Consistent training helps the team maintain accurate records after implementation.
7. Inform Key Stakeholders
Inform investors, lenders, and other stakeholders about the transition and its expected reporting effects. Explain the conversion date, major adjustments, and changes in financial statements. Clear communication helps stakeholders compare results and understand the business’s updated financial position.
Simplify Your Cash Basis Accounting with HashMicro’s All-in-One Solution
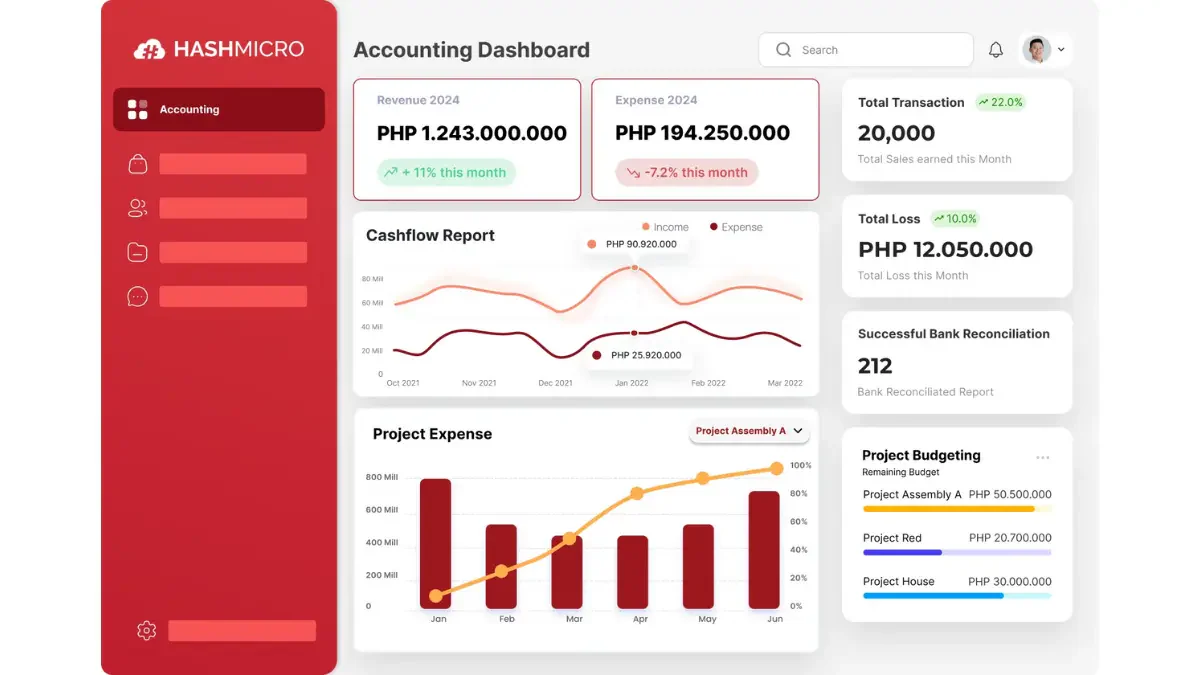
Cash basis accounting helps small businesses record income and expenses when money changes hands. As transaction volume grows, manual tracking can create delays and errors. Accounting Software from HashMicro centralizes cash movement, financial records, and daily accounting tasks in one system.
Key Features of HashMicro’s Accounting Software:
- Real-time bank integration: Record payments and receipts promptly to support accurate cash reconciliation.
- Cash flow-focused invoicing: Track invoices, monitor collections, and follow up on delayed payments.
- Multi-dimensional cash reporting: Review cash inflows and outflows by branch, department, or project.
- Payables, budgeting, and forecasting: Manage vendor payments, compare budgets with actual results, and plan future cash needs.
- Financial reporting and internal controls: Generate organized reports, support tax preparation, and match transactions for better accuracy and traceability.
See how HashMicro can streamline cash-to-cash processes, reduce manual errors, improve financial visibility, and support tax reporting by trying its demo. Its centralized interface also helps finance teams monitor spending, manage accounting tasks, and maintain more consistent records as the business grows.
Conclusion
Cash basis accounting offers a simple way to record income and expenses when cash changes hands. It suits small businesses with straightforward transactions, steady cash flow, and limited financial obligations. However, businesses with large inventories, credit sales, complex liabilities, or external funding needs may require accrual accounting.
Cash basis accounting records income when received and expenses when paid, giving small businesses a clear view of daily cash flow. However, it can overlook unpaid invoices, outstanding bills, inventory costs, and future obligations. As businesses grow, stronger records and systems may support a transition to accrual accounting.
As your business grows, the right tools can improve recordkeeping, cash visibility, and financial planning. Schedule a free consultation with HashMicro to discuss accounting solutions that support your current processes and future reporting needs.
FAQ About Cash Basis Accounting
A cash-basis profit and loss statement reports revenue when customers pay and expenses when the business pays them. It excludes unpaid invoices, unpaid bills, and other earned or incurred amounts. Therefore, the reported profit reflects cash movement during the period rather than the full economic performance.
Yes. A business can issue invoices, set due dates, and follow up with customers while using cash basis accounting. The invoice records the amount owed, but the sale generally enters cash-basis income only when payment is received. Keep an unpaid-invoice schedule for collection control.
Under cash basis accounting, record a credit card purchase when you pay the card issuer, not when the transaction first appears on the card statement. Record customer income when payment reaches the business. Track transaction and payment dates separately to keep unpaid card balances visible.
Cash basis accounting may show inventory-related payments when the business pays suppliers, but separate stock records remain necessary. Track quantities, purchase costs, stock counts, spoilage, and adjustments. These records support pricing decisions, replenishment planning, tax preparation, and a clearer view of inventory commitments.
Keep sales receipts, supplier invoices, bank statements, payroll records, tax documents, and proof of payment for every transaction. Cash basis accounting depends on payment dates, so supporting documents should show when money was received or paid. Organized records simplify reconciliation, tax preparation, and future method changes.