



 Limited to 100 registrants
If your inventory turnover ratio looks healthy while stock keeps piling up in the warehouse, the problem is usually not the ratio itself, but the number underneath it. The average inventory formula tells you how much stock your business typically holds over a period, instead of how much it happened to hold on one particular day.
According to IAS 2 Inventories from the IFRS Foundation, which PFRS follows, businesses must apply the same cost formula consistently to inventories of a similar nature and use. Once that measurement base is inconsistent, the average you calculate from it stops being comparable across periods.
The consequence shows up directly in your reports. Average inventory is the denominator behind inventory turnover and days inventory outstanding. Get the average wrong, and both of those numbers quietly tell you a story that is not true and usually a more comfortable one than reality.
Key Takeaways
Average inventory shows the stock a business typically holds across a period, so turnover and DSI are based on normal inventory levels instead of a single-day balance.
In the worked example below, a Quezon City distributor gets an average inventory of ₱1,550,000 for the year.
The standard formula becomes less reliable when stock moves seasonally, sits across several branches, or includes newly launched SKUs with incomplete inventory history.
Spreadsheets can handle a simple two-point calculation, but multi-branch and monthly inventory tracking needs software to keep balances, costs, and ratios current.
What Is Average Inventory?
Average inventory is the typical value of stock a business holds over an accounting period, calculated by averaging the inventory balance at the start and the end of that period.
That same average also helps you understand the cost side of overstock: storage, insurance, shrinkage, and capital tied up in unsold goods all feed into inventory holding cost.
For example, December 31 stock’s count is a photograph taken on a single day. If that day falls right after a Christmas restock, your stock looks enormous. If it falls right after a clearance sale, it looks tiny. Neither picture describes your year.
Once you have the number, you use it for two things: measuring how fast stock moves through your business, and checking whether the working capital tied up in inventory is proportionate to your sales. Both are covered later in this guide.
The Average Inventory Formula
The formula is easy. Finding the two numbers is where most people get stuck, so here is exactly where to look.
Ending inventory: the closing inventory balance on your balance sheet, or the total value from your year-end physical count. See ending inventory for the full calculation.
Beginning inventory: this is simply last period's ending inventory. They should be the same number. If they are not, someone posted an adjusting entry, and you need to find it before you go any further. Our guide to beginning inventory walks through this.
If you run a perpetual inventory system: your balance is live at any cut-off date. You can pull twelve monthly figures instead of two, which opens up much more accurate methods.
If you run a periodic inventory system: you only have counts at fixed intervals. In that case the two-point formula may genuinely be your only option, and that is fine as long as you know its limits.
One warning before you calculate. Your average is only as reliable as the cost method behind those two balances. If your opening balance was valued using the FIFO method and your closing balance using weighted average cost, you are averaging two things that were never measured the same way. Fix your inventory valuation first, then calculate.
How to Calculate Average Inventory: A Worked Example in Pesos
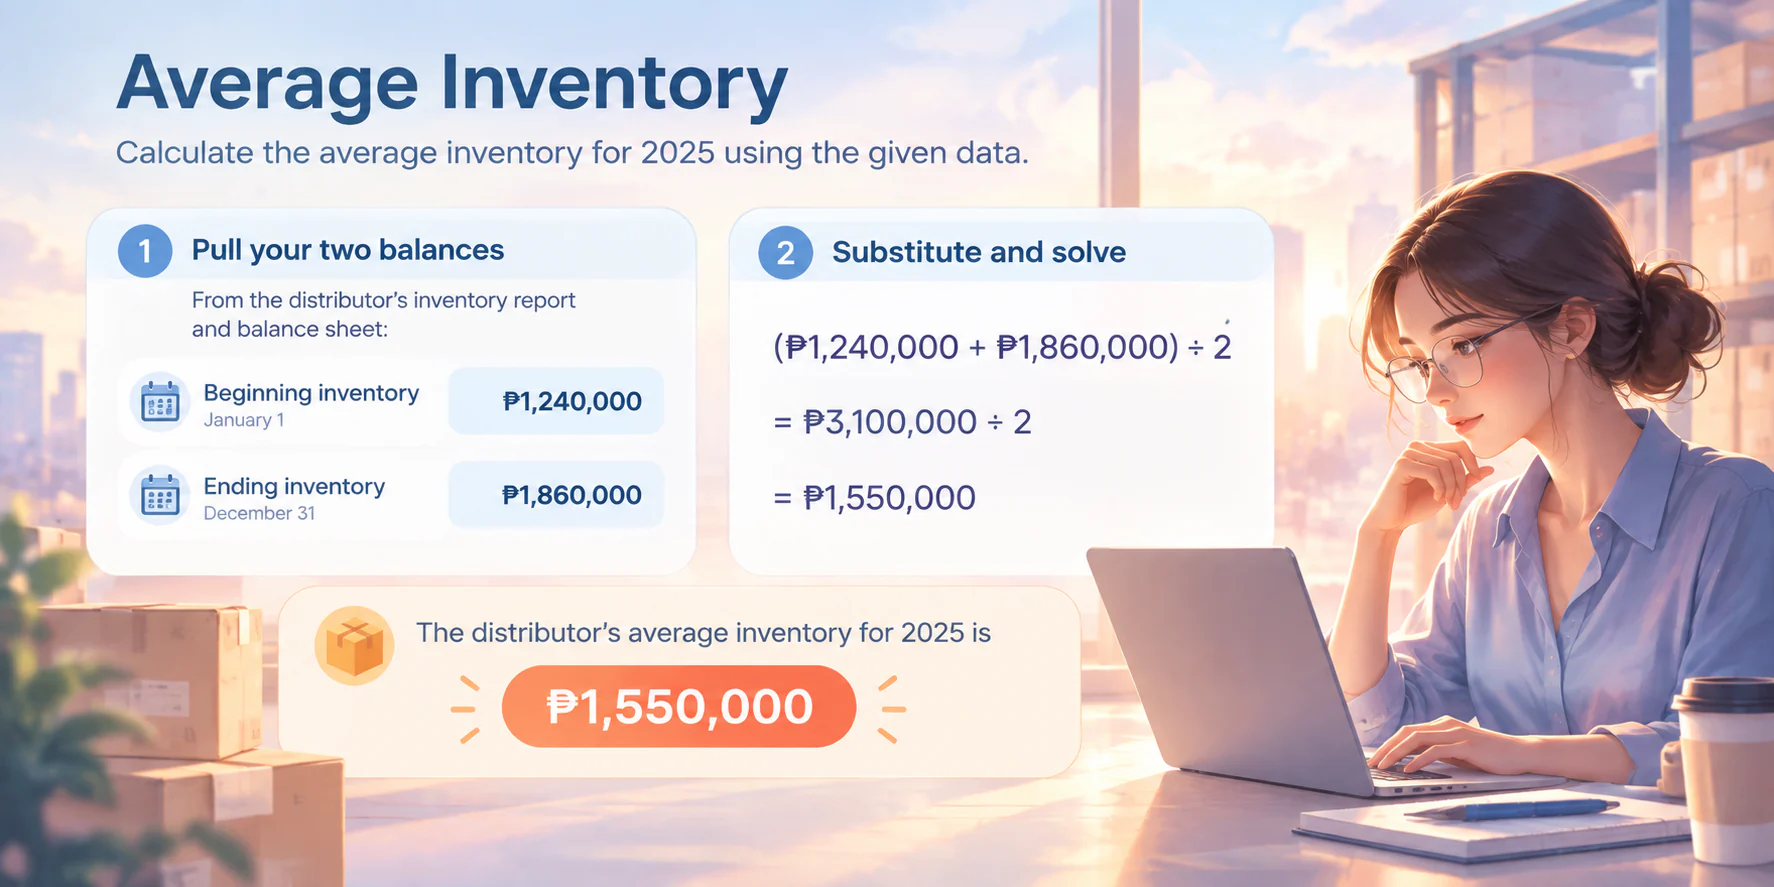
Our example is a mid-sized dry-goods distributor in Quezon City, with stock sitting in three locations: a main QC warehouse, a Cebu branch, and a Davao branch. We are looking at the full 2025 calendar year.
Step 1: Pull your two balances
From the distributor's inventory report and balance sheet:
Beginning inventory, January 1: ₱1,240,000
Ending inventory, December 31: ₱1,860,000
Step 2: Substitute and solve
Write it out fully. Do not skip the middle line, it is the one that catches arithmetic errors.
(₱1,240,000 + ₱1,860,000) ÷ 2
= ₱3,100,000 ÷ 2
= ₱1,550,000
The distributor's average inventory for 2025 is ₱1,550,000.
Step 3: Now check it against reality
Here is where most articles stop. Let us keep going, because the distributor uses a perpetual inventory system, those month-end balances are available without waiting for another physical count.
| Month | Closing stock | Month | Closing stock |
|---|---|---|---|
| Jan 1 (opening) | ₱1,240,000 | Jul | ₱1,280,000 |
| Jan | ₱1,180,000 | Aug | ₱1,350,000 |
| Feb | ₱1,150,000 | Sep | ₱1,620,000 |
| Mar | ₱1,210,000 | Oct | ₱1,980,000 |
| Apr | ₱1,190,000 | Nov | ₱2,340,000 |
| May | ₱1,260,000 | Dec | ₱1,860,000 |
| Jun | ₱1,300,000 | Total, 13 points | ₱18,960,000 |
| Two-point average | ₱1,550,000 | 13-point average | ₱1,458,462 |
Divide ₱18,960,000 by 13 data points and you get ₱1,458,462. That is ₱91,538 lower than the two-point answer, an overstatement of 6.3%.
The reason is visible in the table. Stock climbed from September through November as the business prepared for Christmas, then dropped again by December 31. The two-point formula only ever looks at January and December, so it never sees the build-up at all. It just sees a year that started low and ended higher.
3 Average Inventory Calculation Methods by Business Situations
A business using a periodic inventory system may only have quarterly or year-end balances, so the number of sampling points depends on how often it counts stock.
1. Multi-period (monthly or quarterly) method
Add every period-end balance, including your opening balance, then divide by the number of data points, exactly what we did with the thirteen monthly figures above. Quarterly works too when monthly is too much: ₱1,240,000 + ₱1,210,000 + ₱1,300,000 + ₱1,620,000 + ₱1,860,000 = ₱7,230,000 ÷ 5 points = ₱1,446,000, still within ₱12,462 of the monthly answer.
Use this whenever your business has a visible seasonal pattern. More sampling points means a more honest average.
2. Weighted average cost method
This one works at a different scale per unit, not per balance sheet. Say a café in the same distribution network buys arabica beans: 40 kg opening stock at ₱520, then 60 kg at ₱545, then 50 kg at ₱560. That is 150 kg for a total of ₱81,500, which gives a weighted average cost of ₱543.33 per kg.
This answers a different question. It tells you what a unit of your stock is worth, not how much stock you typically hold. Those are two different questions, and mixing them up is a common reporting error. Businesses that track cost layer by layer use the FIFO method instead, which can produce a different ending inventory figure from the same purchase history.
3. Moving average method
Same coffee, but recalculated after every single receipt. Start with 40 kg at ₱520 (₱20,800), receive 60 kg at ₱545 (₱32,700), and your 100 kg is now worth ₱53,500, a moving cost of ₱535.00 per kg. Issue 70 kg at that rate, receive another 50 kg at ₱560, and the remaining 80 kg carries a cost of ₱550.63 per kg.
This is the most accurate of the three, and it is also the one nobody maintains by hand. A perpetual system runs it automatically in the background on every goods receipt.
When the Average Inventory Formula Misleads You
An overstated average inventory understates your turnover ratio. A lower turnover ratio makes a slow-moving business look healthier than it is, which delays the decision to clear slow-moving inventory while it still has value.
Three situations in particular break the two-point formula.
1. Seasonal peaks: Q4 and the ber-months
Philippine retail, F&B, and distribution businesses start building stock in September and usually peak in November. By December 31, much of it has already sold through. This is the exact pattern that produced the gap in our example.
That is exactly what produced the ₱91,538 gap in our example. The two-point formula samples January and December and misses the entire ber-months build-up in between. If your business has a visible Q4 cycle, sample monthly. Our guide to seasonal inventory covers the planning side of this.
2. Multi-branch and multi-warehouse businesses
The rule here is simple: consolidate first, then average. Add up the beginning balances across every location, add up the ending balances, then apply the formula once.
For our distributor across QC, Cebu, and Davao, the beginning balances of ₱640,000, ₱380,000, and ₱220,000 total ₱1,240,000. The ending balances of ₱980,000, ₱520,000, and ₱360,000 total ₱1,860,000. Applied once, that gives the same ₱1,550,000 we calculated earlier.
Now here is the mistake almost nobody warns you about. If you instead calculate each branch's average separately ₱810,000, ₱450,000, and ₱290,000, then average those three figures, you get ₱516,667. That number is not your company's average inventory. It is the average size of a branch. Reporting it to a lender or an auditor means reporting something that does not exist. Consolidating properly is one of the harder parts of warehouse inventory management.
3. Fast-moving and newly launched SKUs
A product you launched in August has no meaningful beginning inventory for the year. Its average comes out structurally low, and its turnover ratio looks unrealistically good as a result. Calculate new SKUs from their first full month in stock, not from your fiscal year start.
How Is Average Inventory Used in Financial Analysis?
Inventory turnover ratio
Divide COGS by average inventory. For our distributor, ₱9,300,000 ÷ ₱1,550,000 = 6.0x. But use the more accurate ₱1,458,462 and you get 6.38x instead in the same business, two different performance stories, purely because of how the average was calculated. Full detail in our guide to the inventory turnover ratio.
Days inventory outstanding
Divide 365 by your turnover ratio. At 6.0x that is 60.8 days; at 6.38x it is 57.2 days. A 3.6-day difference in how long your cash sits inside stock before it converts back to revenue. See days sales in inventory for the full breakdown.
Why Use Inventory Management Software Instead of Spreadsheets?
A spreadsheet handles a two-point calculation perfectly well. It stops working at the scale this article just walked through where hundreds of SKUs across several branches, sampled every month. Here is what changes when the system does the work:
Live inventory balances at any cut-off date, so monthly sampling costs you nothing
A consolidated view across branches and warehouses, calculated correctly by default
Automatic moving average costing on every receipt
Turnover and DSI computed from the accurate average rather than a two-point estimate
If your stock sits across more than one location, an inventory management system removes the manual reconciliation this article just described.
Conclusion
Average inventory formula is (Beginning + Ending) ÷ 2. For our Quezon City distributor, that is ₱1,550,000 which is a number you can calculate in about ten seconds.
The formula was never the hard part. The sampling decision behind it is. Two data points or thirteen, one location or three, fiscal year or first full month, those choices decide whether your turnover ratio tells you the truth about your business or a comfortable version of it.
If your stock moves seasonally or sits across multiple branches, HashMicro inventory management software keeps that average accurate without the monthly spreadsheet work.
FAQ Around Average Inventory
Derive it from the COGS equation: Beginning Inventory = COGS + Ending Inventory − Purchases. Then apply the standard formula. If your records exist, last period's ending inventory is always this period's beginning inventory, so check there first.
No. Ending inventory is a single-date balance that appears on your balance sheet. Average inventory smooths two or more balances across a period and does not appear on the balance sheet at all, it is a calculation used for ratio analysis.
Monthly for seasonal or multi-branch businesses, and quarterly at minimum for everyone else. An annual two-point calculation is only defensible for a business whose stock levels stay genuinely flat throughout the year.