
Business registration is often treated as complete once the trade name, lease, and first commercial agreement are in place. However, a transaction can still be delayed when the business cannot issue a compliant invoice or official receipt. For finance leaders, this creates a direct compliance gap between commercial readiness and BIR registration.
The Philippine Statistics Authority reported 1,105,722 operating establishments in the country based on the preliminary 2023 Updating of the List of Establishments. With that scale of formal business activity, securing the correct business TIN is not only an administrative step but a control point for invoicing, banking, vendor accreditation, and tax filing.
This guide explains the registration path for sole proprietors, corporations, partnerships, cooperatives, and accounting teams, not employee TIN applications.
This guide explains the registration path for sole proprietors, corporations, partnerships, cooperatives, and accounting teams, not employee TIN applications.
This guide explains the registration path for sole proprietors, corporations, partnerships, cooperatives, and accounting teams, not employee TIN applications.
However, a transaction can still be delayed when the business cannot issue a compliant invoice or official receipt.
However, a transaction can still be delayed when the business cannot issue a compliant invoice or official receipt.
However, a transaction can still be delayed when the business cannot issue a compliant invoice or official receipt.
For finance leaders, this creates a direct compliance gap between commercial readiness and BIR registration.
This guide is for sole proprietors, corporations, partnerships, cooperatives, and accounting teams registering a business TIN, not employees applying for a personal TIN.
It explains which BIR form to use, what documents to prepare, how to file, and what to set up after the TIN is issued.
Then the client asks for a compliant invoice or official receipt, and the transaction suddenly stalls.
For many new Philippine businesses, the real blocker is not the launch itself, but the missing BIR registration behind it.
Key Takeaways
A TIN is required for a business before it can issue invoices, official receipts, open a corporate bank account, or become an official vendor.
Use BIR Form 1901 for a sole proprietor and BIR Form 1903 for a corporation, partnership, or cooperative.
Prepare documents according to the business type because incomplete files usually mean the process at the RDO must be repeated.
After the TIN is issued, the business must still register books of accounts and handle invoice or receipt authorization.
What a TIN Means for a Registered Business?
A Tax Identification Number is the permanent identifier the BIR uses to connect a business with its tax records. It links every filing, payment, invoice, and receipt to one registered taxpayer profile.
For a registered business, the TIN supports core transactions such as invoice authorization, corporate bank account opening, supplier accreditation, and tax return filing. Without it, the business cannot complete the documentation expected by banks, corporate buyers, and the BIR.
The TIN structure depends on the entity type. A sole proprietor registers the business under the owner’s existing personal TIN, while a corporation or partnership receives a separate entity TIN.
Which BIR Form Applies to Your Business Type
The BIR form you need depends on the legal type of taxpayer being registered. Choosing the wrong form can delay approval because the RDO may return the application and require a corrected submission.
For business registration, the main forms are Form 1901 for individual business taxpayers and Form 1903 for juridical entities. Other BIR forms may appear in search results, but they do not always apply to new business TIN registration.
BIR Form 1901: Sole proprietors, self-employed individuals, professionals, and mixed-income earners
Use Form 1901 if the business is registered under an individual owner. This applies to DTI-registered sole proprietors, licensed professionals, freelancers registering formally, and individuals earning both compensation income and business income.
BIR Form 1903: Corporations, partnerships, cooperatives, associations, and government agencies
Use Form 1903 if the registrant is a separate legal entity. Corporations and partnerships must have SEC registration first, while cooperatives must have CDA registration before proceeding with BIR registration.
BIR Form 1902: Employees earning purely compensation income
Form 1902 is not a business registration route. It is generally used for employees earning compensation income, usually through employer-assisted registration.
BIR Form 1904: One-time taxpayers and ONETT transactions
Form 1904 is also not used for regular business registration. It applies to one-time taxpayer transactions, such as certain property-related or estate-related tax matters.
BIR Form 1905: Updates, RDO transfer, branch registration, or closure
Use Form 1905 when an existing taxpayer needs to update registration details. This includes changes in registered address, RDO transfer, branch registration, or business closure.
BIR Requirements for TIN Registration by Entity Type
Document requirements diverge sharply depending on whether you are registering as an individual or as a juridical entity. Prepare the bundle for your category, not a generic checklist.
Requirements for Sole Proprietors and Professionals
For a single proprietorship, the core of your submission is the proof that the business legally exists and that you occupy the place of business you are declaring.
Accomplished BIR Form 1901
DTI Certificate of Business Name Registration
Mayor's Permit, or the official proof of application if the permit is still in process
Valid government-issued identification showing name, address, and birthdate
Proof of address for the place of business, such as a lease contract or a land title if the property is owned
For licensed professionals, the current PRC identification card or the corresponding professional license
The document most often missing at the counter is proof of the business address. If your place of business is leased, bring the signed contract of lease. If it is your residence, prepare whatever proof of ownership or occupancy the RDO accepts, and confirm the acceptable format with your RDO before you travel.
Requirements for Corporations and Partnerships
Corporate registration requires the incorporation documents plus evidence that the person filing is authorized to act for the entity.
Accomplished BIR Form 1903
SEC Certificate of Incorporation, or SEC Certificate of Recording for partnerships, or CDA Certificate of Registration for cooperatives
Articles of Incorporation and By-Laws
Mayor's Permit, or proof of application
Proof of address for the principal place of business
Board Resolution or Secretary's Certificate naming the authorized representative who will transact with the BIR
Valid identification of the authorized representative
For accounting staff handling this on behalf of the company, the authorization document is the piece that determines whether the RDO will even accept your submission. A Secretary's Certificate that names the representative specifically, rather than a general resolution, moves the process faster.
How to Apply for a TIN Number
After identifying the correct BIR form, the next step is to prepare the filing route and supporting documents. A complete submission helps the RDO validate the business faster and reduces the risk of repeat visits.
Step 1: Identify the RDO for your place of business
Every taxpayer is assigned to a Revenue District Office based on the registered business address. Filing with the wrong RDO can delay the application because that office may not have jurisdiction over the registration.
Confirm the correct RDO code through the BIR website before preparing the application. For businesses with multiple locations, the head office registers with the RDO covering the main office, while each branch registers with the RDO covering that branch.
Step 2: Complete the correct BIR form
Use Form 1901 or Form 1903 based on the business type confirmed in the previous section. Form 1901 applies to sole proprietors and professionals, while Form 1903 applies to corporations, partnerships, cooperatives, and other juridical entities.
Fill in the business activity carefully because it affects tax type classification and future filing obligations. If the business may fall under VAT or percentage tax, confirm the correct classification before submission.
Step 3: Prepare the supporting documents
Use the document checklist that matches the taxpayer type and legal structure. Bring original documents for validation and prepare photocopies for submission.
For sole proprietors, this usually includes the DTI registration and owner identification documents. For corporations, partnerships, and cooperatives, prepare the SEC or CDA registration documents before filing with the BIR.
Step 4: File through the correct channel
The BIR operates the Online Registration and Update System for selected registration and update transactions. However, coverage may vary by registrant type, so check the current online BIR registration guide before assuming the full TIN number application can be completed online.
If online processing is not available for the business category, file directly with the assigned RDO. In-person filing may also be required when original documents need to be presented.
Step 5: Complete the registration obligations
Receiving the TIN and Certificate of Registration does not finish the compliance process. The business must also address books of accounts registration and authority to issue invoices or official receipts.
Confirm with the RDO which items can be completed during the same visit and which require a separate submission. This helps the business avoid gaps between tax registration, invoicing readiness, and filing obligations.
Step 6: Secure the Certificate of Registration
The Certificate of Registration is a core document for banks, corporate clients, and future BIR reviews. Keep the original with the company records and provide scanned copies to the finance or client onboarding team.
Avoid relying on informal processing time estimates. The timeline can vary by RDO and document completeness, so the best preparation is a complete and correctly classified submission.
How to Verify an Existing TIN and Fix Common Registration Errors
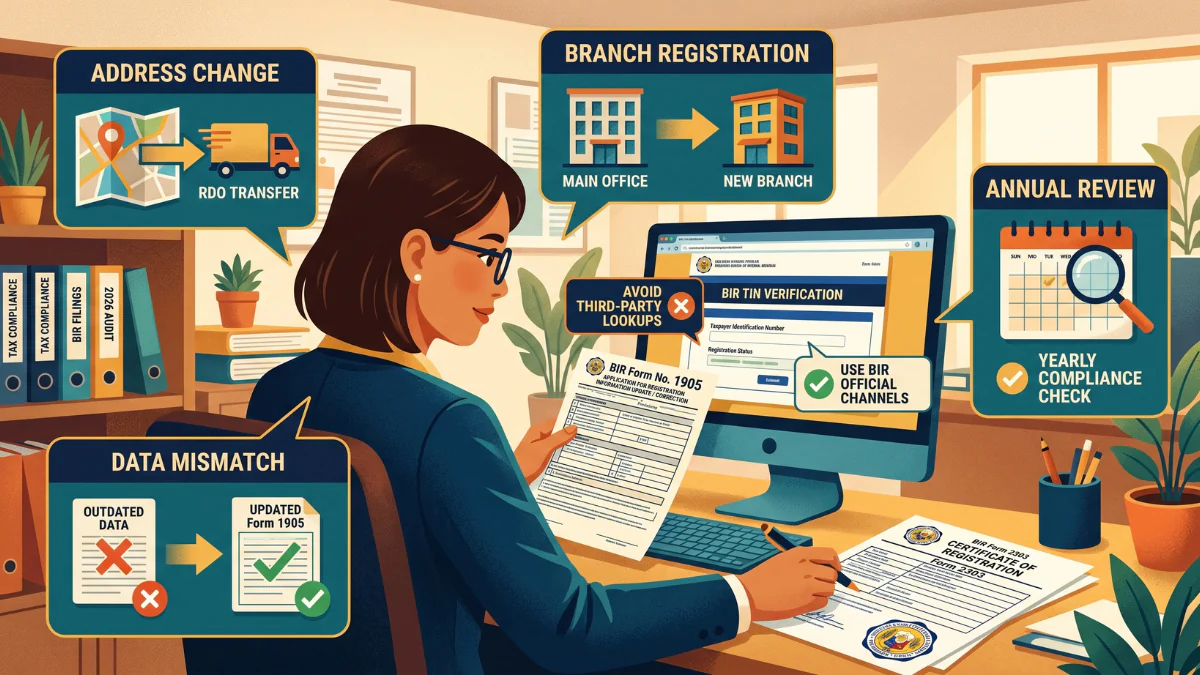
Accounting teams often inherit BIR registration records from a previous staff member without a complete handover. When this happens, the main risk is not only missing paperwork but outdated taxpayer data that can affect audits, banking, client onboarding, and filing accuracy.
If the TIN cannot be located: If the Certificate of Registration is missing, recover the TIN only through the BIR’s official verification channels. Avoid third-party TIN lookup websites because they are not authorized by the BIR and may expose company information.
If registered details no longer match actual operations: Trade name changes, registered activity updates, and tax type changes must be processed through BIR Form 1905. Leaving outdated details on file can create mismatches when the BIR compares the company’s returns with the tax types linked to its TIN.
If the business has relocated: A business address change must be updated with the BIR, especially if the new address falls under another RDO. If the move changes the RDO jurisdiction, process the RDO transfer through BIR Form 1905.
If the company opened a branch: A new branch must be registered with the RDO that covers the branch location. It should not be treated as a simple note under the head office record because clients may request the branch’s own Certificate of Registration.
If the registration record has not been reviewed recently: Review the company’s BIR registration data at least once a year against actual operations. This small control helps prevent routine filing or audit checks from turning into longer compliance issues.
Common TIN Registration Mistakes Philippine Businesses Make
TIN registration mistakes often happen because businesses treat the process as a one-time administrative filing. In practice, each detail affects invoicing, tax filing, banking, vendor onboarding, and audit readiness.
Filing with the wrong RDO: RDO jurisdiction follows the registered business address, not the owner’s home address or the accountant’s office. Confirm the correct RDO code before filing because the rest of the registration process depends on it.
Applying for a second TIN: A sole proprietor who already has a personal TIN must register the business under the same number. Applying again creates a duplicate TIN, which the Tax Code prohibits and penalizes.
Using the wrong BIR form: Form 1901 and Form 1903 are not interchangeable. A sole proprietor should not file Form 1903, and a corporation should not file Form 1901.
Using a personal TIN on corporate sales documents: For corporations, invoices and official receipts must use the entity’s TIN. Using a director’s personal TIN can create issues during the client’s withholding tax processing and weaken credibility with corporate buyers.
Treating TIN issuance as the final step: The Certificate of Registration is not the end of compliance. Businesses must still complete books of accounts registration and secure the authority to issue invoices or official receipts.
Letting registration details become outdated: Address changes, new branches, and changes in registered activity must be updated through BIR Form 1905. If these updates are missed, the company’s filings may no longer match its BIR registration record.
What to Set Up After Your TIN Is Issued
Registration starts a set of ongoing obligations that continue after the TIN and Certificate of Registration are issued. The business must maintain BIR-accepted books of accounts, issue BIR-compliant official receipts, retain transaction records, and file returns based on its registered tax types.
These obligations are manageable when transaction volume is still low. They become harder to control when monthly invoices increase, a second branch opens, or the person managing the spreadsheet-based process leaves.
At that point, a structured accounting system becomes a compliance control, not only an admin tool. HashMicro accounting software helps businesses keep books, invoices, receipts, branch records, and filing reports consistent with the format expected by the BIR.
If the business plans to use a computerized system, review the requirements in our guide to BIR computerized accounting system registration.
Conclusion
Identify your entity type and file the matching form, 1901 for sole proprietors and 1903 for corporations and partnerships. Registering a TIN for a business depends on three decisions made correctly. Identify the entity type, file the matching form, and prepare the complete document bundle before going to the RDO.
The Certificate of Registration should be treated as the start of compliance, not the end of the process. Businesses that stay ready for BIR review are usually the ones that set up proper records from the first invoice instead of reconstructing them later under pressure.
Consult with our expert team for free to see how HashMicro can support your business registration, daily transactions, and long-term BIR compliance through a more structured accounting system.
Consult with our expert team for free to see how HashMicro can support your business registration, daily transactions, and long-term BIR compliance through a more structured accounting system.
Consult with our expert team for free to see how HashMicro can support your business registration, daily transactions, and long-term BIR compliance through a more structured accounting system.
Consult with our expert team for free to see how HashMicro can support your business registration, daily transactions, and long-term BIR compliance through a more structured accounting system.
Consult with our expert team for free to see how HashMicro can support your business registration, daily transactions, and long-term BIR compliance through a more structured accounting system.
FAQ
It depends on the entity type. A sole proprietorship registers under the owner's existing personal TIN, with the business added as a registered activity. A corporation or partnership is a separate juridical person and receives its own TIN, distinct from those of its owners.
Corporations, partnerships, and cooperatives file BIR Form 1903. The entity must already hold its SEC or CDA registration before BIR registration can proceed. Form 1901 applies to sole proprietors and professionals, not to juridical entities.
The BIR operates the Online Registration and Update System for digital registration and updates. Coverage by registrant type has expanded in stages, so confirm on the BIR portal whether your category can complete the process fully online before assuming no RDO visit is required.
The business cannot issue compliant invoices or official receipts, which affects its ability to transact with corporate clients. Penalties for late registration also accrue from the deadline, and exposure typically surfaces during an audit rather than at the time of the omission.
File BIR Form 1905 to update registration details. If the new address falls under a different Revenue District Office, the same form is used to request an RDO transfer. Opening a branch requires separate registration with the RDO covering that branch location.